Some financial advice never really gets tested; it just gets repeated. A parent says it, a coworker says it, someone read it in a book once, and eventually it hardens into a rule nobody questions. The trouble is that money rarely behaves in absolutes, and taxes, credit, debt, and investing all have more nuance than a one-line tip usually allows. Here are 15 pieces of money wisdom that don’t hold up as well as they sound.
1. Carrying a Balance Builds Your Credit
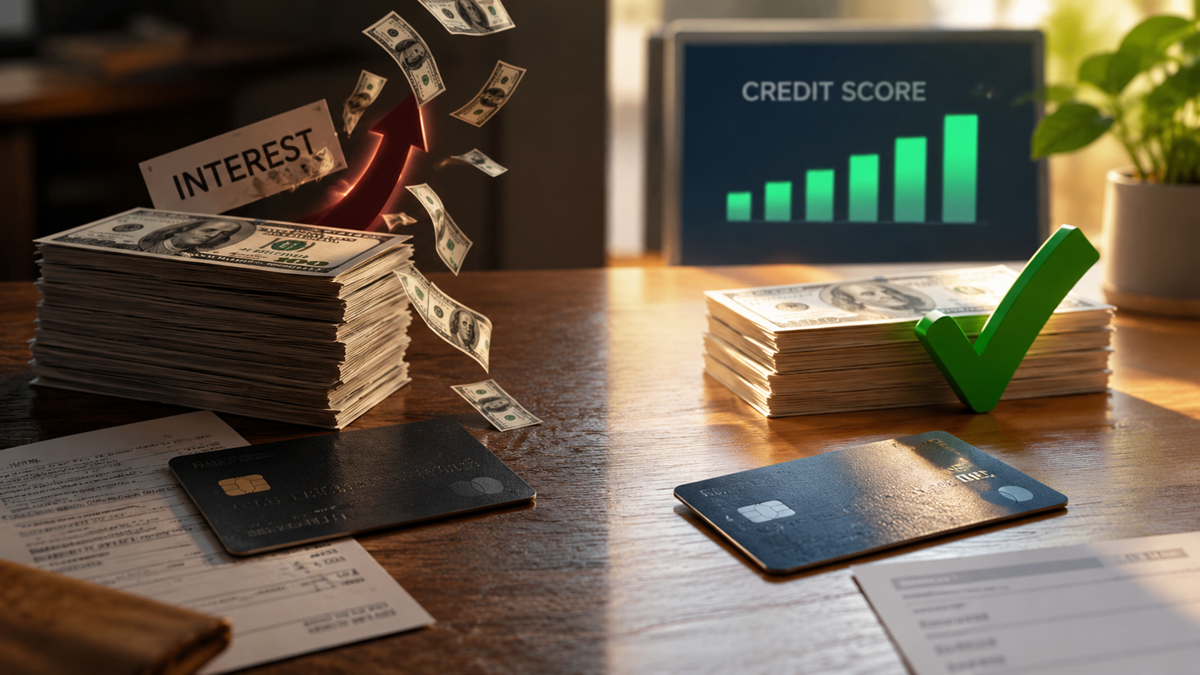
This one costs people real money for no reason. Credit scores respond to payment history, credit usage, and account age, not to whether interest got paid on a balance somebody could have wiped out in full. Paying a card off completely every month still builds the same history, just without the interest charges tacked on.
2. Renting Is Just Throwing Money Away
Rent doesn’t build equity, sure, but “wasted” is a strange word for a roof over your head. It also buys freedom from repairs, property taxes, and the closing costs that come with owning. In an expensive city or for a short stay, renting can be the more sensible math, not the consolation prize.
3. Earning More Can Push You Into a Lower Take-Home Pay
People picture tax brackets like a cliff, where crossing into a new one suddenly taxes every dollar you earn at the higher rate. That’s not how a progressive system works. Only the income sitting inside that new bracket gets taxed at the higher rate, so a raise almost never leaves someone with less money in their pocket because of the bracket itself.
4. Buying a Home Always Beats Renting
Homeownership can be a great wealth builder, and it’s still not automatically the better move in every city or at every stage of life. Mortgage interest, maintenance, insurance, closing costs, and the opportunity cost of tying up a down payment all belong in the math. Someone planning to move again in two years may never stick around long enough for ownership to pay off.
5. You Need a Lot of Money to Start Investing
That idea made more sense before fractional shares and low-cost funds existed. These days, a small, consistent amount going in regularly tends to matter more than showing up with a big first deposit.
Trending on The Scroller
6. All Debt Is Bad Debt
High-interest credit card debt can wreck a budget fast, but lumping every loan into one bucket ignores a lot. A mortgage or a student loan can finance something that would otherwise take years to save for outright. The better question is rarely “debt or no debt”; it’s interest rate, affordability, and what the money is actually buying.
7. Closing an Old Card Helps Your Score
Closing a card you never use feels responsible, and it can backfire. It shrinks your total available credit, which can push up your utilization percentage, and it may erase some of your account history along with it. There are good reasons to close a card, especially an expensive one, but an automatic score boost isn’t one of them.
8. The Stock Market Is Just Gambling
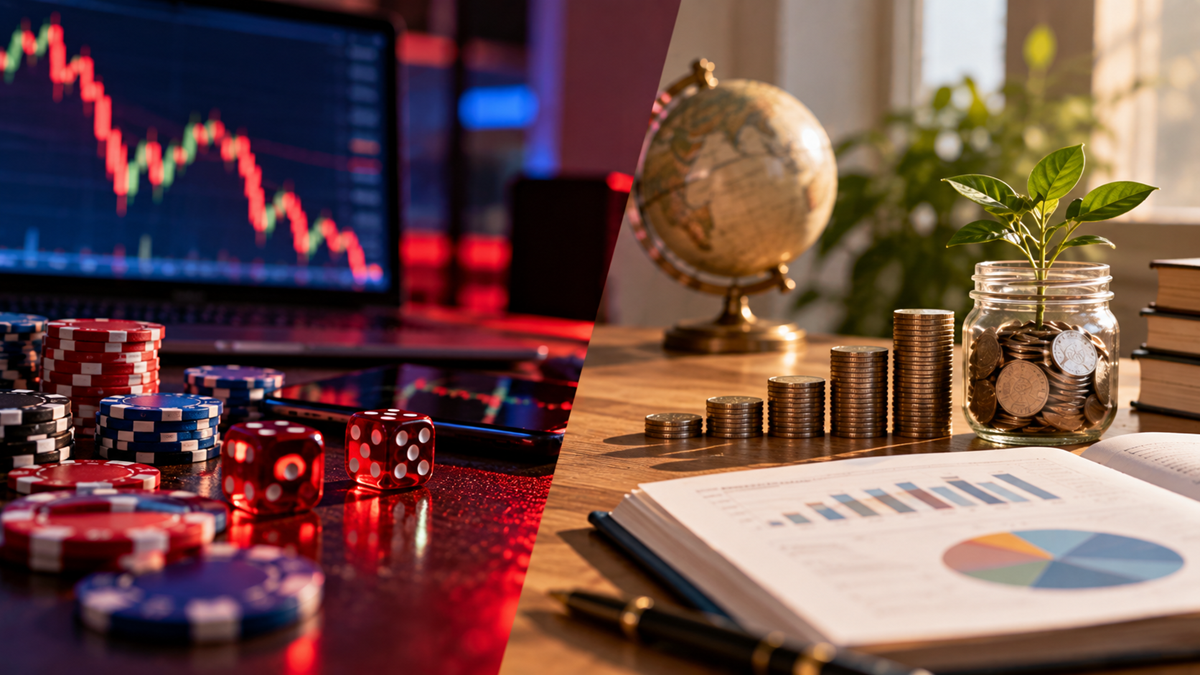
A short-term bet on one volatile stock can feel a lot like a casino trip. Owning a diversified slice of real businesses for decades is a different game entirely, since you’re buying a claim on companies actually producing revenue and profit. Risk doesn’t vanish, but the two aren’t running on the same logic.
Sign up for our newsletter
9. A Big Salary Means Someone’s Rich
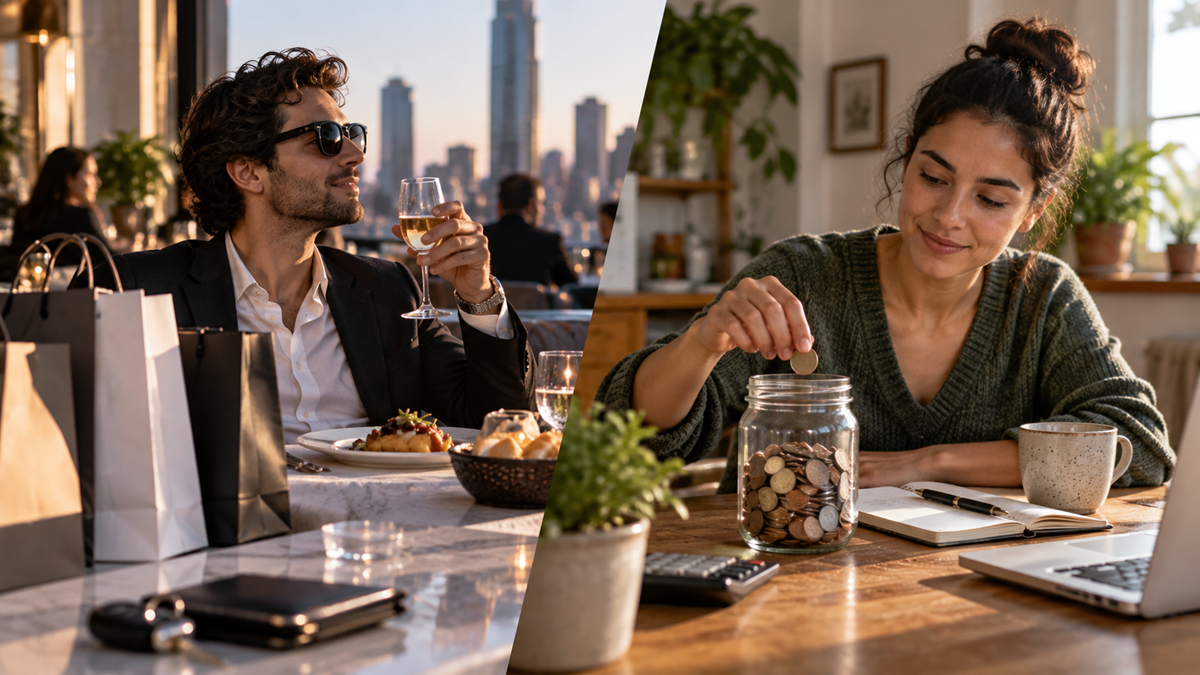
Income measures what comes in, not what’s left. Plenty of high earners spend it all, or more, and end up with thin savings once taxes and debt payments are through. Someone with a modest paycheck who consistently saves a slice of it can end up further ahead.
10. Cash Is Completely Safe
It doesn’t swing in value the way a stock portfolio can, so it feels bulletproof. But cash sitting still loses purchasing power as prices rise around it. Great for emergencies and short-term needs, not the same thing as risk-free.
11. A Tax Refund Is Free Money
It arrives like a bonus, one lump sum landing in an account. Really, it usually just means too much was withheld from paychecks over the year. Getting it back is nice, but it was already your money to begin with.
12. You Have to Put 20 Percent Down on a Home
Twenty percent became so familiar that people treat it like a rule instead of one option among several. Plenty of mortgage programs allow smaller down payments for qualified buyers, though that can come with added costs like mortgage insurance. Hitting that number has its perks, but waiting for it isn’t mandatory.
13. Checking Your Credit Score Hurts It
Looking at your own score is treated as a soft inquiry and doesn’t ding your credit. Applying for new credit is a different story; that can trigger a hard inquiry. Keeping tabs on your own numbers isn’t the same as shopping for five new credit cards in a week.
14. Skip the Coffee, and You’ll Get Rich
Small purchases add up; nobody’s arguing that. But the numbers that really move a budget are usually housing, transportation, debt interest, and income growth, not a five-dollar latte. Cutting every small joy while ignoring a car payment that’s way too high is solving the wrong problem.
15. Smart Investors Can Time the Crash
Every crash looks obvious in hindsight, with warning signs lined up neatly on a chart. In the moment, though, signals conflict and prices can keep climbing long after the first warnings show up. Long-term investing doesn’t require nailing every peak and valley, and trying to usually does more harm than good.
In the mood for more?
Check out 15 Money Myths That Sound True Until You Look Closer, or take a look at 15 Industries Quietly Making Enormous Amounts of Money. If you want to see more personal finance stories, you can check out 15 Financial Habits People Learn in Their 40s and Wish They Started at 25.